Our Market Operations Weekly Report contains the latest information about the electricity market, including security of supply, wholesale price trends and system capacity.
It is published every Tuesday. Click here to receive the report via email every week.
If you have any comments or questions please contact the Market Operations Team at [email protected].
Latest Report / More Information
|
Image

|
|
Current Storage Positions
Overview
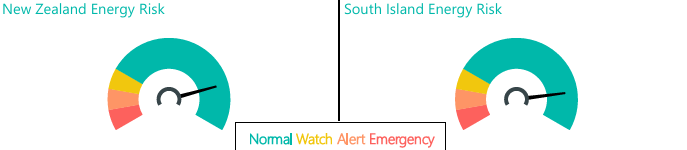
National hydro storage remained above the 90th percentile last week, with inflow events throughout the country. Although solar and wind generation reduced last week, renewable generation remains above the annual average, at 97% of the mix.
In this week's insight we look at the effects on hydro generation and storage from the introduction of more renewable generation.
Security of Supply and Capacity
Energy
National hydro storage increased to 126% of the seasonal average from 125% the week prior. South Island storage remained at 133% while North Island storage increased from 74% to 82%.
Capacity
Residual generation was healthy last week. The lowest residual was 784 MW on the morning of Wednesday 4 November.
The N-1-G margins in the NZGB forecast are at healthy levels through to early January. Within seven days we monitor these more closely through the market schedules. The latest NZGB report is available on the NZGB website.
Electricity Market Commentary
Weekly Demand
Total demand decreased last week to 747 GWh from 770 GWh the week prior. The highest demand peak occurred at 8:00 am on Monday 4 November at 5,397 MW with cooler temperatures in parts of the country.
Weekly Prices
Wholesale electricity spot prices increased last week with the average Ōtāhuhu price up to $94/MWh from $36/MWh the previous week. The Ōtāhuhu price peaked at $300/MWh at 7:30 pm on Wednesday 4 November, coinciding with
constrained HVDC northward flow and lower North Island wind generation.
Periods of inter-island energy price separation occurred throughout the week during periods of high HVDC northward transfer, with outages of lower North Island grid equipment lowering the northward transfer limit.
Generation Mix
Solar and wind generation both dropped last week to 3% and 9% respectively, from 4% and 15% the week prior. This coincided with a pickup in hydro generation last week from 56% of the mix to 62%. The remaining mix stayed relatively consistent from the week prior.
HVDC
HVDC flows last week were almost entirely northward, consistent with above average South Island hydro storage. Northward transfer decreased on 3 November coinciding with lower overnight demand and high North Island wind generation and again over the weekend when demand was lower. In total 117 GWh was transferred north.
Consultations
The consultation on the TSO:DSO coordination: operations requirements paper has now closed. Formal submissions have now been published.
Ancillary Services Procurement Plan updated
The Authority approved the System Operator's changes to the Ancillary Services Procurement Plan on 23 October 2026. The new procurement plan became effective on 21 October 2026.